Decide who you’re for and what you’ll do for them
The most useful decision you’ll make is who your firm is for. “Small businesses” is a market. “Trades businesses in my region that have outgrown a shoebox of receipts” is a niche, and it tells you what to offer, what to charge, what software your clients probably use and where to find them.
A niche can be an industry, a type of client (owner-managed companies, landlords, not-for-profits), a service (tax planning, bookkeeping and payroll, advisory) or a mix. The best ones usually come from work you’ve already done. Years on hospitality clients at your last firm means you know their problems and their busy season, and that is what a new client is buying.
Once you have the niche, list your services in two groups:
- Core recurring work that pays the bills every month or year: compliance, bookkeeping, payroll, tax returns.
- Project and advisory work that grows from the recurring relationship: planning, restructures, forecasting, systems help.
Keep the first list short. It’s easier to add a service once clients ask for it than to support one nobody buys.
Check your credentials and registration before you take on clients
What you need before you can offer services to the public depends on where you practise, which body you belong to and the work you plan to do. Tax work, audit and the right to call yourself by a particular title can each carry their own rules. We won’t list requirements here because they change and they differ by person, so go to the source:What you need before you can offer services to the public depends on where you practice, which body you belong to and the work you plan to do. Tax work, audit and the right to call yourself by a particular title can each carry their own rules. We won’t list requirements here because they change and they differ by person, so go to the source:
- Australia: CPA Australia or Chartered Accountants Australia and New Zealand (CA ANZ), depending on your membership.
- UK: the ICAEW or the ACCA, depending on your membership.
- US: your state board of accountancy, which sets the rules for CPAs in your state.
Ask them three questions: what you need before you take on clients, what insurance they expect you to hold, and what applies to the specific services on your list. Get the answers in writing and keep them with your business plan. Ask a lawyer about your business structure and engagement terms too.
Choose a pricing approach you can explain in one sentence
You’ll be tempted to price low to win your first clients. Resist it. It’s much harder to raise a price than to start at the right one.
Three approaches are common:
- Fixed fees per job or package, agreed up front. Clients like the certainty, and you’re rewarded for working efficiently.
- Monthly subscriptions that bundle recurring work, often with a set number of meetings or support included.
- Hourly billing, which is simple to start with but rewards slow work and makes clients wary of calling you.
Whichever you choose, write the scope down in a proposal or engagement letter and agree it before the work starts. A clear scope is what lets you see when a job has grown and have the conversation about it. Many new firms find that extra work first comes up in a client meeting, so it helps to have a habit of turning that conversation into a proposal the same day.
Build a small tech stack that connects
A new firm doesn’t need much software, but it does need the pieces to connect. At minimum you’ll want a ledger (usually whichever one your clients already use), practice management for jobs, deadlines and the client record, proposals and engagement, email and calendar, and somewhere to keep notes from client meetings.
We cover each of those jobs, and what to look for in each, in our guide to software for accounting firms. The short version for a new firm: choose practice management early, because it becomes the client record everything else feeds into, and check that each new tool connects to it before you buy.
Win your first clients
Most new firms find their first clients through people who already know their work. Before you go out on your own, and within whatever your current employment terms allow, think about:
- Your network. Former colleagues, past clients you’re allowed to approach, and people in your niche who’ve asked you for advice.
- Referral partners. Lawyers, financial planners, mortgage brokers and business bankers who serve the same clients you want. Offer to be useful to them first.
- Your niche’s own channels. Industry associations, local business groups and the online communities where your clients ask questions.
- A simple website that says who you help, what you do and how to book a first conversation.
Once the firm is trading, our guide on how to get accounting clients covers the ways that keep new clients coming.
Design the client experience from the first meeting
Early on, the way you run meetings and onboarding is your marketing. A client who feels looked after tells people. A client who has to chase you for what was agreed does too.
Run every meeting with an agenda. Send it with the invite, say what the meeting is for and what you need the client to bring. Our client meeting agenda template has versions for a first meeting, tax planning and reviews.
Onboard in the same order every time. Engagement letter, identity checks, access to the client’s ledger and records, and a kickoff meeting. A written list stops steps getting missed in a busy week. Use our client onboarding checklist as a starting point.
Follow up the same day. Send a short email after each meeting with what was discussed, what you’ll do and what the client owes you, with dates. Here’s the follow-up email we recommend.
Keep a file note. Record the advice you gave and the decisions the client made against their record, where the next person on the client can find it.
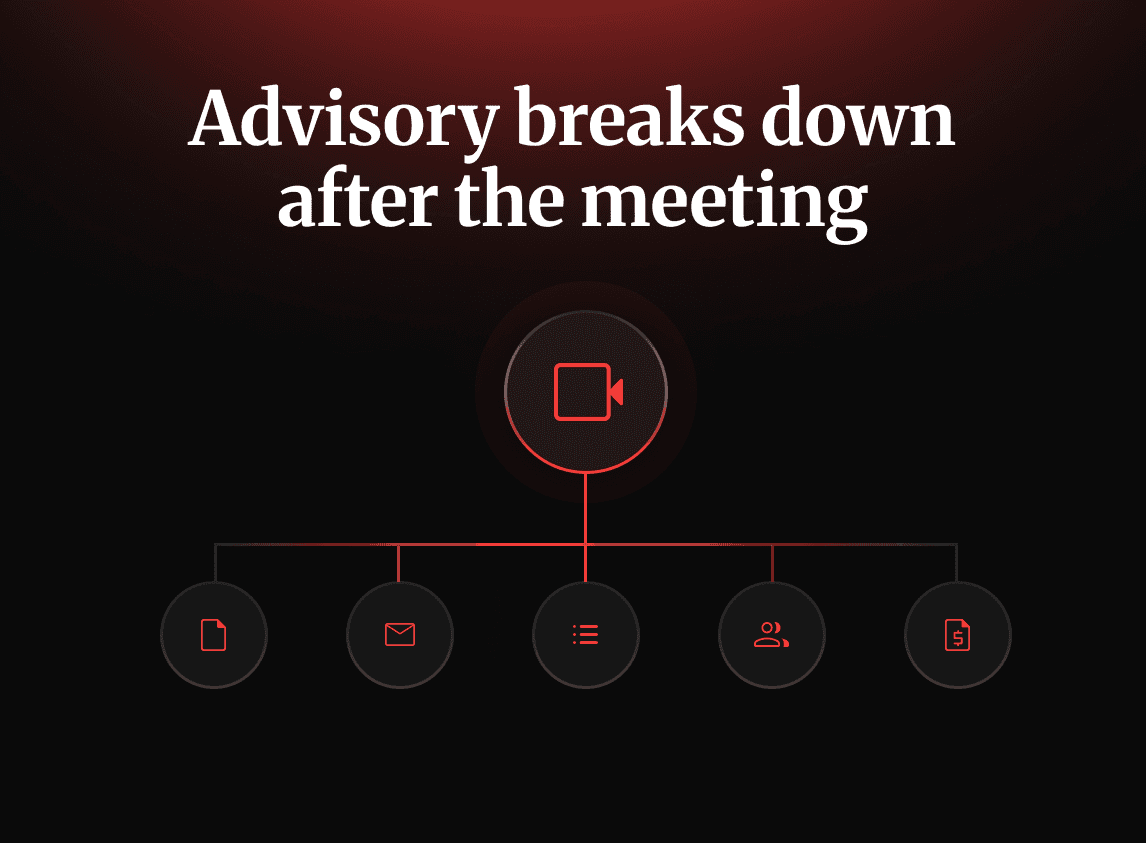
When you’re the only person in the firm, that write-up is the part that slips first, so this is where we’d mention what we build. Vinyl records your client meetings on Zoom, Microsoft Teams, Google Meet or in person, writes the notes and action items, and drafts the follow-up email for you to check. You click Send from your own Gmail or Outlook, or save it as a draft.
A one-page business plan outline for an accounting firm
A business plan for an accounting firm doesn’t need to be long. One page you’ll actually reread beats a document nobody opens. Copy this outline and fill in each line.
ACCOUNTING FIRM BUSINESS PLAN (ONE PAGE)

Firm name:
Founder(s):
Date:

1. WHO WE SERVE
   Niche (industry, client type or service):
   Typical client (size, structure, what they struggle with):
   Where they are (region, online, both):

2. WHAT WE DO
   Core recurring services:
   Project and advisory services:
   What we will not do:

3. WHY THEY'LL CHOOSE US
   Experience we bring to this niche:
   How we work differently (response time, meetings, reporting):

4. CREDENTIALS AND COMPLIANCE
   Professional body or state board checked:
   What they told us we need before taking clients:
   Insurance:
   Business structure and engagement terms (adviser):

5. PRICING
   Pricing approach (fixed, subscription, hourly):
   Packages and what each includes:
   How we handle work outside scope:

6. TECH STACK
   Ledger(s) we support:
   Practice management:
   Proposals and engagement:
   Email and calendar:
   Meeting notes and follow-ups:

7. FIRST CLIENTS
   Network contacts to approach:
   Referral partners to meet:
   Niche channels and events:
   Website and booking link:

8. CLIENT EXPERIENCE
   First meeting agenda:
   Onboarding checklist:
   Follow-up after every meeting (who, when):
   Where file notes live:

9. MONEY
   Start-up costs (list each):
   Monthly running costs (list each):
   Personal runway (months we can cover):
   Revenue goal for year one, and how many clients that needs:

10. MILESTONES
   First 90 days:
   End of year one:
   When we'd hire our first team member:
Fill in the money section with your own quotes and numbers, not averages from the internet. Your costs depend on your country, your software choices and your insurer, and the figure that matters is how many months you can cover before the firm pays you.
Frequently Asked Questions
How do I start an accounting firm from scratch?
Choose a niche and a short list of services, check with your professional body or state board what you need before you take on clients, set a pricing approach, choose software that connects, and line up your first clients through your network and referral partners.
How do I start a CPA firm in the US?
Start with your state board of accountancy, which sets the rules for CPAs and CPA firms in your state, and ask what applies to the services you plan to offer. The rest of the plan is the same as any accounting firm: niche, services, pricing, software, first clients and client experience.
What should a business plan for an accounting firm include?
Who you serve, what you do for them, why they’ll choose you, your credentials and compliance checks, pricing, tech stack, how you’ll win your first clients, your client experience, your costs and runway, and milestones for the first year. The outline above covers each one on a single page.
What software does a new accounting firm need?
A ledger, practice management, proposals and engagement, email and calendar, and a way to keep notes and follow-ups from client meetings. Our software for accounting firms guide covers what to look for in each.
How do new accounting firms find clients?
Mostly through people who already know their work: former colleagues and clients they’re allowed to approach, referral partners who serve the same clients, and the industry groups in their niche. A clear niche makes each of those conversations easier.